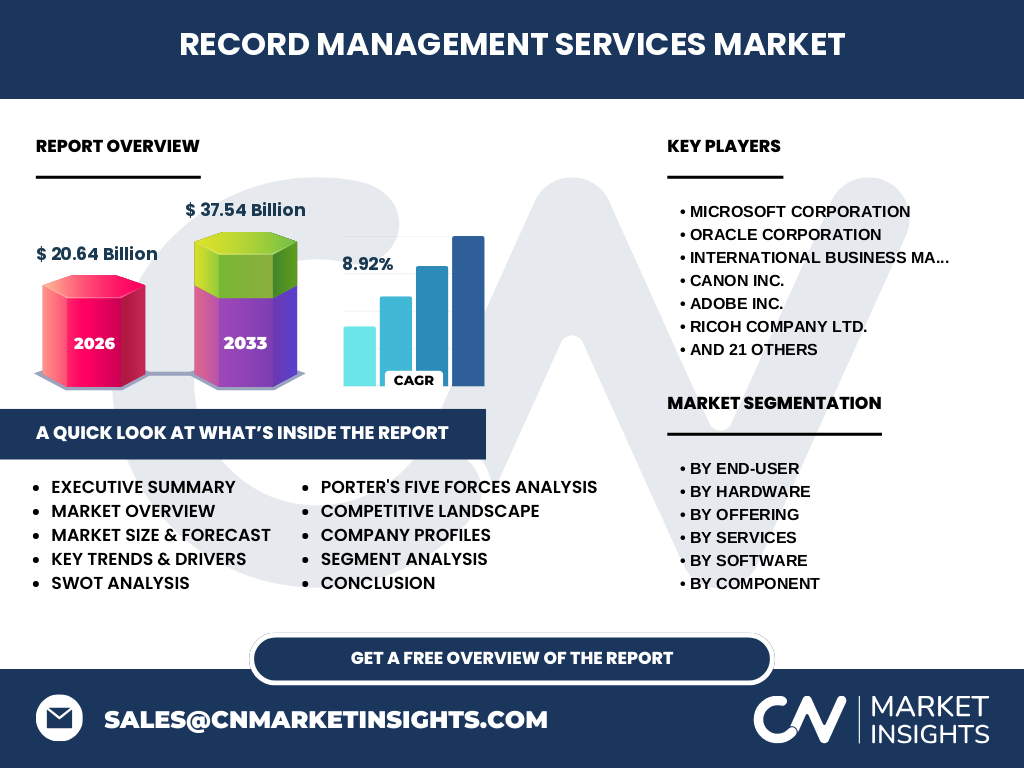
Market overview of the Record Management Services Market
Our analysis indicates the Record Management Services Market is valued at 20.64 Billion in 2026. This sector encompasses physical storage, cloud solutions, and digitization vital for navigating stringent data compliance frameworks established by bodies like HIPAA and GDPR.
Key market drivers, restraints, challenges, and opportunities
Stringent regulatory compliance acts as the primary catalyst, forcing enterprises to adopt advanced information governance. However, high migration costs and legacy system integration barriers restrain rapid cloud adoption, presenting monetization opportunities for hybrid software and service providers.
Structural Growth Trends in Information Governance
The market is witnessing a rapid shift toward automated records lifecycle management and AI-driven document classification. Enterprises increasingly demand seamless integration between Document Management Software and cloud repositories to mitigate rising cybersecurity threats and streamline audits.
COVID-19 impact analysis and recovery trajectory
The pandemic drastically accelerated remote work adoption, forcing an abrupt pivot from physical storage to cloud-based digitization workflows. Recovery has been robust, driven by permanent enterprise structural changes prioritizing distributed access security over traditional on-premises filing systems.
Competitive Benchmarking and Market Concentration
The landscape features a blend of legacy physical storage giants like Iron Mountain Incorporated and agile software innovators like Microsoft Corporation and Box Inc. Market concentration is moderate, with enterprise tech leaders pushing cloud integration while specialized vendors target compliance niches.
Executive Summary of the Record Management Services Market industry trends
Driven by robust digital transformation initiatives across BFSI and healthcare, the sector is poised for explosive expansion. Our proprietary research highlights a projected leap from 20.64 Billion in 2026 to 37.54 Billion by 2033, underpinned by an impressive 8.92% CAGR.
Long-term market forecast from 2027 to 2033
Based on our research, the Record Management Services Market market size will expand from 20.64 Billion in 2026 to reach 37.54 Billion by 2033. This trajectory represents a steady 8.92% CAGR, fueled by escalating data generation and automated compliance demands.
Segmentation analysis across hardware, software, and services
The market divides across components including software, hardware, and services. Offerings range from Digitization and cloud storage to secure shredding. End-users span BFSI, healthcare, and government, deploying tools via on-premises and cloud architectures to manage diverse enterprise requirements.
Geographic distribution and regional performance
Regional adoption varies significantly based on local data privacy laws and IT infrastructure maturity. North America leads in cloud software adoption, while Europe prioritizes stringent GDPR-compliant physical and digital archiving solutions, followed by expanding Asia-Pacific enterprise hubs.
In-depth regional review of compliance-driven adoption
North America commands significant market share due to early tech adoption and strict SEC and HIPAA mandates. Meanwhile, the European market exhibits accelerated demand for specialized compliance management software, driven by rigorous regional data sovereignty regulations and cross-border transfer restrictions.
Strategic positioning of leading industry players
Industry giants like Oracle Corporation, Adobe Inc., and OpenText Corporation leverage comprehensive software ecosystems. Meanwhile, specialized firms such as DocuWare GmbH and M-Files Corporation focus on bespoke workflow automation and metadata-driven document archiving.
Porter's Five Forces analysis of competitive intensity
Bargaining power of buyers is moderate due to high switching costs associated with enterprise data migrations. Threat of new entrants remains low owing to stringent security certifications required, whereas rivalry among established cloud and physical storage giants is exceptionally intense.
SWOT analysis of the Record Management Services Market
Strengths include sticky enterprise client bases and essential regulatory utility. Weaknesses involve high initial hardware deployment costs. Opportunities lie in AI-powered workflow automation, while threats stem from sophisticated cyber threats targeting centralized cloud repositories.
Value chain analysis from infrastructure to end-users
The value chain originates with raw data storage hardware and document scanners, moves through Records Lifecycle Management Software developers, and flows via managed service providers to end-users in legal, government, and healthcare sectors requiring secure destruction.
Investment insights and high-potential areas
Investors should target niche software innovators specializing in automated workflow and compliance management. Our analysis indicates that firms bridging physical storage legacy systems with agile cloud infrastructure represent the highest-potential targets for strategic M&A activity.
Conclusion and key takeaways for strategic planners
The Record Management Services Market analysis confirms robust health, scaling at an 8.92% CAGR toward 37.54 Billion by 2033. Organizations that successfully integrate hybrid storage, AI-driven governance, and stringent security will dominate this expanding landscape.
Research methodology and data triangulation
Our baseline estimates are rigorously triangulated by combining primary stakeholder interviews with C-level executives, trade registry datasets, and secondary macroeconomic indicators. This multi-tiered approach ensures high fidelity in forecasting the Record Management Services Market industry trends.
Scope of the report and coverage parameters
This report evaluates the global market across deployment modes, organization sizes, and end-user verticals from 2026 to 2033. Limitations include localized regulatory shifts that may unpredictably alter regional compliance software adoption curves and hardware supply chains.
Recent developments in partnerships and product launches
Recent market activities feature major cloud integrations and strategic mergers among enterprise software leaders like IBM, Xerox Holdings Corporation, and Access Information Management Inc. These moves focus on enhancing AI-driven document discovery and automated records destruction capabilities.